So You Want to Become a Financial Advisor After 30
The licensing path, the year-plus of supervised training, and the prior jobs — teaching, nursing, retail management — that translate best into advice work.
Quick answer
- A bachelor's degree in any field is the typical entry requirement and prior related experience usually is not needed (U.S. Bureau of Labor Statistics, 2025), so a teaching, nursing or retail-management background does not disqualify you.
- New advisors need long-term on-the-job training under senior advisors that usually lasts more than a year (U.S. Bureau of Labor Statistics, 2025) — budget six to twelve months of living expenses for the earnings gap before that training pays.
- CFP certification requires 6,000 hours of relevant professional financial planning experience or 4,000 apprenticeship hours under a CFP professional (CFP Board requirement, via Kaplan Financial Education), so start counting hours from your first day in a junior seat.
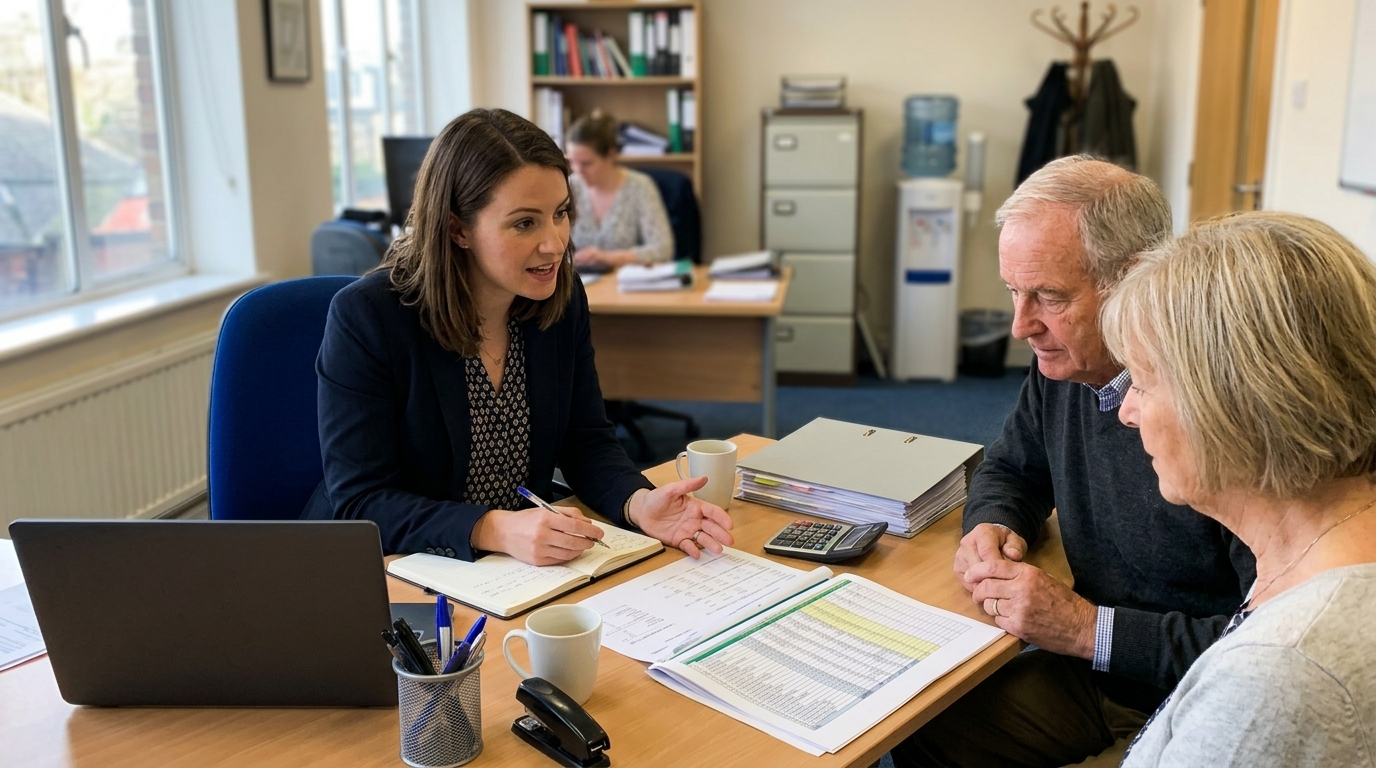
Becoming a financial advisor in your thirties, forties or fifties is a normal route into the job. The U.S. Bureau of Labor Statistics (2025) says typical entry-level education is a bachelor's degree in no particular field, and that work experience in a related occupation is not typically required — what is required is long-term on-the-job training under senior advisors, usually lasting more than a year.
Plan on roughly two to four years from your first exam to a client base that supports you, with licensing filling the first three to nine months. The median annual wage for personal financial advisors was $105,070 in May 2025, or $50.51 per hour (U.S. Bureau of Labor Statistics, 2025) — but that median reflects advisors with established books, not people in month four.
What the Work Actually Involves
Strip away the brochure language and the job is meetings, follow-up and paperwork, in that order. The weekly hours below are planning estimates to help you picture the job, not published figures.
Client meetings. Advisors usually meet each client at least once a year to update them on investments and adjust the financial plan (U.S. Bureau of Labor Statistics, 2025). Once you have a book, that tends to mean six to ten hours a week in review meetings of 45 to 90 minutes each, plus roughly half an hour of prep per meeting pulling performance numbers.
Discovery and prospecting. New advisors spend the biggest block here — commonly ten to fifteen hours a week — explaining services to potential clients and interviewing them to gather financial information and assess their financial status (U.S. Bureau of Labor Statistics, 2025; CareerOneStop, U.S. Department of Labor). That is seminars, referral calls, coffee meetings and unanswered voicemails. It shrinks as a book builds and never disappears.
Plan building and research. Expect four to eight hours a week researching investment opportunities, recommending or selecting investments, and planning for circumstances like education funding or retirement (U.S. Bureau of Labor Statistics, 2025). A first full plan for a new household can take several hours of modelling before anyone sees it.
Monitoring and compliance. Another three to five hours goes on monitoring accounts and documenting advice. Advisors at small firms managing client investments register with state regulators; those at large firms register with the SEC (U.S. Bureau of Labor Statistics, 2025), and that supervision shapes how much of your week is spent writing things down.
Who This Career Change Suits
- Elementary and high school teachers — you already explain growth and risk to anxious, under-informed people. Educating clients on investment options and risks is a core duty (U.S. Bureau of Labor Statistics, 2025).
- Registered nurses and hospice staff — you have sat with families through medical crises and end-of-life finances. Retirement and long-term care conversations use the same emotional register.
- Retail or restaurant managers — you have run a P&L, hit targets you did not set, and worked a pipeline of walk-in strangers. Early advisor work is business development with a compliance manual.
- Insurance agents and claims adjusters — you have held product licences and know suitability questions, and you understand commission income that starts slow.
- Accountants, bookkeepers and tax preparers — you read a 1040 faster than most advisors ever will, which shortens the technical learning curve in CFP coursework.
- Separating military officers and senior NCOs — you are used to credentialing gates and supervised qualification periods, and a pension can cushion the income gap.
- Real estate agents — you have survived variable income, you build referral networks, and you handle the largest transaction most households make.
- Social workers and HR benefits specialists — you are comfortable asking intrusive money questions and holding confidential information, which is most of a discovery meeting.
It suits you less if you need a predictable paycheque every two weeks, or if outreach to people you know socially feels unbearable.
Transferable Skills That Carry Over
| Prior Career | Skill | How It Applies Here |
|---|---|---|
| Elementary teacher | Breaking complex ideas into plain steps | Educating clients on investment options and the risks involved, and explaining services to prospects who have never had an advisor (U.S. Bureau of Labor Statistics, 2025) |
| Registered nurse | Structured intake and triage | Interviewing clients to gather financial information and assess their financial status (CareerOneStop, U.S. Department of Labor) |
| Retail store manager | Pipeline and target management | Prospecting and running a book against the production thresholds most firms set during training |
| Tax preparer or bookkeeper | Reading returns and cash-flow statements | Plan construction and retirement projections, plus faster progress through a CFP Board Registered Education Program (Kaplan Financial Education) |
| Insurance agent | Product licensing and suitability analysis | Knowing why your licence mix matters when you buy or sell stocks, bonds or insurance policies (U.S. Bureau of Labor Statistics, 2025) |
| Military logistics or personnel NCO | Operating inside regulated, documented systems | Compliance recordkeeping and registration with state regulators or the SEC |
| Social worker | Difficult conversations about money and family | Retirement, inheritance and caregiving planning, where the obstacle is rarely the arithmetic |
How to Get Started
- Check the baseline before you spend anything. Typical entry-level education is a bachelor's degree with no specific field usually required, and related work experience is not typically required (U.S. Bureau of Labor Statistics, 2025). If you hold a degree in anything, you clear the first gate.
- Decide which side of the business you want. Advisors who directly buy or sell stocks, bonds or insurance policies, or who give specific investment advice, may need a combination of licences depending on the products they sell (U.S. Bureau of Labor Statistics, 2025). Fee-for-advice work and securities sales lead to different exams.
- Look up your state's requirements. CareerOneStop's License Finder, run by the U.S. Department of Labor, lists licence records for personal financial advisors by state. Registration differs: small firms managing client investments register with state regulators, large firms with the SEC (U.S. Bureau of Labor Statistics, 2025).
- Pass your first exam. The Series 65 has 130 scored questions plus 10 pretest questions, 180 minutes, and at least 92 correct answers to pass. If a broker-dealer hires you, you will take the Series 7 and the Series 66 — 100 scored questions plus 10 unscored, 150 minutes, at least 73 of 100 correct, with the Series 7 as a co-requisite (FINRA). The Series 66 fulfils the requirements of both the Series 63 and Series 65 (Kaplan Financial Education).
- Get hired into a supervised junior seat. Paraplanner, associate advisor and client-service roles are where the long-term on-the-job training under senior advisors happens, usually lasting more than a year (U.S. Bureau of Labor Statistics, 2025). This is where your first paycheque comes from.
- Start the CFP clock on day one. CFP Board requires either 6,000 hours of relevant professional financial planning experience or 4,000 hours of apprenticeship experience under a CFP professional, and you must complete a CFP Board Registered Education Program, with CFP Board notified, before sitting the exam (Kaplan Financial Education).
- Sit the CFP exam when coursework and hours line up. The exam is 170 multiple-choice questions, and the pass rate cited for March 2026 was 67% (300 Hours, 2026).
- Move from subsidised pay to your own book. For most career changers that step takes two to four years from the first exam.
Costs and Time Commitment
Exam, prep and tuition fees change and differ by provider and state, so check FINRA, your state regulator and CFP Board for current amounts before you commit. Durations below are planning estimates.
| Item | Typical Cost | Typical Time |
|---|---|---|
| Series 65 exam prep and sitting | Exam and prep-course fees published by FINRA and prep providers | 2-3 months of part-time study; 180-minute exam, 92 of 130 scored questions to pass |
| Series 7 plus Series 66 route | Usually sponsored and paid by the hiring firm | 3-6 months for both; Series 66 is 150 minutes, 73 of 100 scored questions to pass (FINRA) |
| CFP Board Registered Education Program | Tuition set by the provider; CFP Board publishes exam fees separately | 12-18 months part-time alongside work (Kaplan Financial Education) |
| CFP experience requirement | No direct fee | 6,000 hours of professional experience, or 4,000 apprenticeship hours under a CFP professional (Kaplan Financial Education) |
| Income gap during the build-up | Budget 6-12 months of living expenses in cash | Supervised training usually runs more than a year (U.S. Bureau of Labor Statistics, 2025); pay often sits below your old job for 12-24 months |
| Failed-exam delay | Repeat exam fee | Retake waits for NASAA exams such as the Series 65/66 become 30 days after a first and second failure and 60 days after a third, effective 4 January 2027, down from 180 days (FINRA) |
Frequently asked questions
Am I too old to start at 42 or 50?
The occupation does not gatekeep on age the way some technical fields do: typical entry-level education is a bachelor's degree in no particular field, and related work experience is not typically required (U.S. Bureau of Labor Statistics, 2025). The friction sits in the 45-60 range, where hiring managers sometimes assume you will not sit through training that usually lasts more than a year (U.S. Bureau of Labor Statistics, 2025). Say in the interview that you expect a year-plus of supervised training and have six to twelve months of expenses set aside; it removes the objection before it is raised.
Should I take the Series 65 or the Series 7 and 66?
Take the Series 65 if you plan to give advice for a fee and want to sit an exam without a sponsoring firm — 130 scored questions in 180 minutes, with 92 correct needed to pass. Take the Series 7 plus Series 66 if a broker-dealer will sponsor you; the Series 66 has no prerequisite, but the Series 7 is a co-requisite (FINRA). The Series 66 fulfils the requirements of both the Series 63 and Series 65 (Kaplan Financial Education), which saves you an exam later.
How hard is the CFP exam for a career changer?
It is a 170-question multiple-choice exam, and the pass rate cited for March 2026 was 67%, with rates holding between 62% and 68% since the 2022 blueprint change and averaging 65% over the prior four years (300 Hours, 2026). You cannot sit it until you have completed a CFP Board Registered Education Program and CFP Board has been notified (Kaplan Financial Education). Most candidates studying alongside a full-time advisory job give it several months of evenings and weekends.
What will I actually earn while I am building a book?
The median annual wage for personal financial advisors was $105,070 in May 2025, or $50.51 per hour (U.S. Bureau of Labor Statistics, 2025), but that is the midpoint across advisors at every stage, including those with decades of clients. Early pay is usually a training salary, a draw against future commissions, or salary-plus-bonus that steps down as your production rises, and it differs sharply by firm model and by state. Check current wage data for your state and metro area through the Bureau of Labor Statistics before you resign from anything.
Is the job market growing?
Employment of personal financial advisors is projected to grow from 2025 to 2035, but slower than the average for all occupations, with most annual openings coming from workers transferring occupations or leaving the labour force (U.S. Bureau of Labor Statistics, 2025). For a career changer that means seats open mainly through turnover, which favours people willing to start as a paraplanner or associate during the year-plus training period. Check licence requirements for your own state using CareerOneStop's License Finder, since rules differ between state regulators and the SEC.
Sources
- U.S. Bureau of Labor Statistics — Personal Financial Advisors : Occupational Outlook Handbook (2025)
- FINRA — Series 66 – Uniform Combined State Law Exam
Written by
Desmond writes about the mechanics of job searching: resumes, interviews, the long silence after applying. He's fascinated by how much of getting hired depends on luck dressed up as skill.